

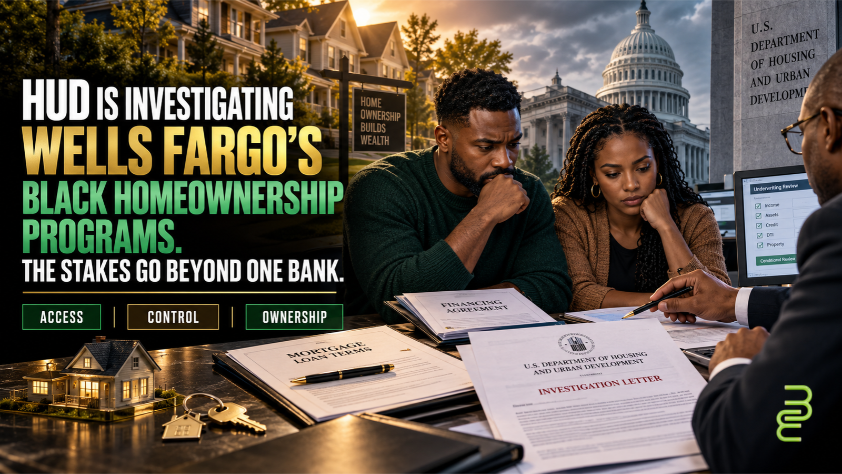
For nearly a decade, Wells Fargo publicly positioned targeted mortgage initiatives as part of an effort to expand Black homeownership.
Now the federal government is investigating whether some of those efforts crossed a legal line.
The U.S. Department of Housing and Urban Development (HUD) notified Wells Fargo CEO Charles Scharf on October 7 that its Office of Special Investigations is examining the bank’s mortgage lending policies, practices and programs for potential violations of the Fair Housing Act.
HUD says the investigation will determine whether Wells Fargo violated — or intends to violate — federal prohibitions against discrimination in residential real-estate transactions.
No violation has been established. HUD
That distinction matters.
But so does the economic question sitting underneath the legal dispute: If financial institutions pull back from programs designed to address racial gaps in mortgage access, what replaces them?
For Black households, that question reaches far beyond one bank.
Wells Fargo made Black homeownership a stated lending priority
In 2017, Wells Fargo announced a commitment to provide $60 billion in home-purchase loans with the goal of helping create at least 250,000 additional African American homeowners by 2027.
The bank expanded its efforts in 2022.
According to HUD’s investigation letter, Wells Fargo said it would identify eligible Black homeowners who could benefit from refinancing and committed $150 million toward lowering mortgage rates and refinancing costs for qualifying homeowners.
HUD is now examining whether those practices improperly made race a factor in the availability or terms of mortgage credit.
The agency’s October 7 letter also directs Wells Fargo to preserve records related to its mortgage policies and says HUD will issue initial information requests within ten business days.
If investigators ultimately find reasonable cause to believe the bank violated federal civil-rights law, the matter could lead to discrimination charges or referral to the Justice Department.
Reuters reported that the inquiry is part of a broader HUD review of similar initiatives at other banks. Reuters
That is why this is bigger than Wells Fargo.
The rules around targeted credit have already changed
The investigation is arriving during a broader federal shift in how race-conscious credit programs are treated.
Special Purpose Credit Programs, or SPCPs, have long existed within federal credit regulation as a mechanism through which certain lenders can design programs to address defined economic or social needs.
But the regulatory environment changed sharply in 2026.
In April, the Consumer Financial Protection Bureau amended Regulation B, which implements the Equal Credit Opportunity Act.
Among the changes, the CFPB prohibited creditors from using race, color, national origin or sex as common characteristics for determining eligibility in covered Special Purpose Credit Programs. Consumer Financial Protection Bureau
Then, in August, HUD and six other federal agencies rescinded a 2022 interagency statement that had encouraged broader use of SPCPs. HUD
HUD is now applying that changing enforcement philosophy to programs Wells Fargo publicly promoted over several years.
The result is not simply a legal argument over terminology. It is a question about how lenders will respond when the regulatory risk around targeted interventions rises.
Mortgage access is access to an asset
For BlackEconomicDevelopment.com, the central issue is ownership.
A mortgage is not merely a financial product. It is one of the principal gateways into residential property ownership.
That creates an economic chain:
Mortgage access ? homeownership ? equity ? borrowing capacity ? assets that can be transferred, leveraged or inherited.
Not every homeowner builds wealth at the same rate. Property values, interest costs, taxes, maintenance expenses, location and timing all matter.
But the ability to obtain affordable mortgage financing still determines who gets an opportunity to enter that ownership system in the first place.
That is what gives the Wells Fargo investigation consequences beyond banking compliance.
Federal regulators control the legal boundaries.
Banks control product design, underwriting standards and the allocation of mortgage capital.
Households seeking to buy or refinance a home operate inside rules they do not set.
When any one of those layers changes, access can change with it.
Equal rules and equal access are not necessarily the same question
The federal government’s position is increasingly clear: race cannot be used to determine who receives particular credit products or terms merely because the program is intended to address a racial disparity.
HUD’s investigation will test Wells Fargo’s specific conduct against the Fair Housing Act. The CFPB’s 2026 changes have separately narrowed how protected characteristics can be used within certain special-purpose lending programs.
But eliminating race-conscious eligibility does not eliminate the underlying economic conditions that prompted lenders to create these programs.
That leaves financial institutions with a harder design problem.
How do they expand mortgage access among borrowers and communities that have been underserved without using eligibility standards federal regulators now reject?
Possible approaches can focus on economic characteristics rather than race: income, geography, first-generation homeownership, property location, down-payment barriers or other legally permissible indicators of disadvantage.
Whether those approaches reach the same households at comparable scale is an empirical question.
And that is where the economic consequences of this policy shift will become measurable.
Banks now have to price regulatory risk into access
Banks do not make lending-policy decisions in a vacuum.
Legal uncertainty creates cost.
Investigations require lawyers, compliance teams, data reviews and executive attention. Potential enforcement creates additional financial and reputational exposure.
That changes incentives.
A bank deciding whether to launch a specialized mortgage initiative is not only calculating credit risk.
It is also evaluating regulatory risk: Could a program designed to close an access gap later become evidence in an enforcement action?
One possible response is better program design.
Another is institutional retreat.
If large lenders choose the second option, the economic effect will not be measured primarily by the number of diversity programs that disappear. It will be measured by what happens to borrowers who previously used them.
- Do comparable financing pathways remain?
- Do lenders replace them with income- or geography-based products?
- Do community banks, credit unions, housing-finance agencies or nonprofit programs fill the gap?
- Or does access simply narrow?
Those are the questions worth tracking.
The biggest issue is who controls the gate to ownership
The Wells Fargo investigation is ultimately about more than a bank’s past statements about racial equity.
It exposes a basic reality of the housing economy: households may own the property after closing, but financial institutions and regulators largely control the gate they must pass through to get there.
HUD controls fair-housing enforcement.
The CFPB sets important credit rules.
Banks decide which mortgage products to offer, how they are structured and which borrowers qualify.
Borrowers face the consequences of those decisions downstream.
That makes this investigation an ownership story as much as a legal one.
The critical measure will not be whether a particular corporate diversity initiative survives.
It will be whether a changing fair-lending regime produces a mortgage market that can expand legitimate access to ownership without unlawful discrimination — and whether Black households have effective pathways into that market when the new rules settle.
HUD has opened the investigation.
The next economic question is what banks do because of it.
That is where the stakes move from policy to pocket.
What to Watch Next
Watch for HUD’s findings on Wells Fargo, whether other banks face formal investigations, and how lenders redesign targeted mortgage programs under the CFPB’s revised rules.
The most consequential signal will be practical: whether replacement products expand, preserve or reduce access to affordable mortgage capital.
Stay with The Economics Behind It for the ownership, access and wealth consequences behind the headlines.
Latest posts by normbond (see all)
- HUD Is Investigating Wells Fargo’s Black Homeownership Programs. The Stakes Go Beyond One Bank. - October 8, 2026
- How Warren Thompson Turned Corporate Contracts Into a Black-Owned Hospitality Empire - October 7, 2026
- Beyoncé Funded Cécred Herself. Now the Real Test Is Global Distribution. - October 2, 2026